
Invest for the Future
Cash feels safe.
Over time it quietly shrinks.
If you have a lump sum sitting in a savings account, you have already made an investment decision. This site explains the alternatives in plain English so you can decide whether it is still the right one.
Written for people with money sitting still
The problem with standing still
Cash does not fall. What it buys does.
A savings balance is a flat line, and a flat line feels like safety. Move the years and watch what happens to the same money underneath it.
Still in the account
£50,000
What it actually buys
£37,205
£12,795 of spending power, gone, and the balance never moved. Interest paid on the account reduces that gap, and only closes it if the rate beats inflation.
Each square is one per cent of what you started with. The hollow ones are what inflation has taken, without a penny leaving your account.
An illustration of arithmetic, not a forecast. It shows what a stated rate of inflation does to a stated sum over time. It is not a prediction of inflation, it takes no account of interest earned or tax, and it is not advice. Read it alongside our guide to what inflation is.
Let’s look at the main options
Between a savings account and the stock market, there is a middle.
Most people know the two ends. Cash, which does not move much and does not grow much. Shares, which grow more over long periods and fall a long way on the journey.
Bonds sit between them. A bond is a loan: you lend money to a government or a company, they pay you interest for a fixed period, and they aim to repay you at the end. Bond markets are the largest in the world, and historically bonds have moved less sharply than shares, though their value can still rise and fall.
For someone holding a lump sum who wants more than a savings rate but does not want the ride that shares give, this is the part of the market worth understanding first. By investing in a strategic bond fund you can diversify your risk across a collection of investments.
The guides
What’s on this site
Eighteen guides, in four groups. Each one is a single page you can read on its own, share, or come back to. Nothing is hidden behind a form and nothing asks you for your details.
- Your goalsAn emergency fund, a house deposit, a wedding, an inheritance.7 guides
- How toThe order to do things in, and how to research a fund properly.5 guides
- What isFixed income, equities, inflation and interest, in plain English.7 guides
- Where to investISAs, investment platforms, and a directory of where to look.2 guides
The four most read
If you only read four
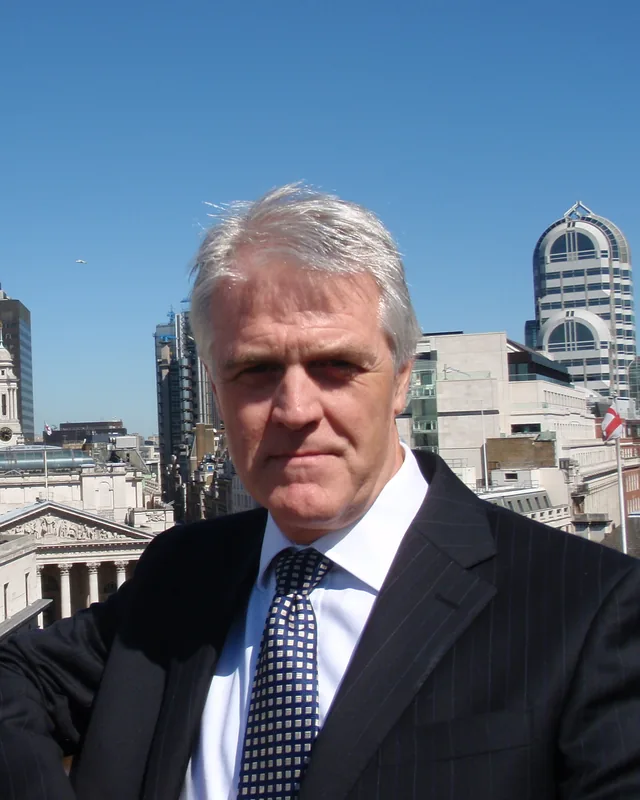
Why this site exists
“The Invest for the Future campaign was launched in April 2026 at the London Stock Exchange. The aim is to support the public in making informed financial decisions. I wanted to give something back, and to support the initiatives that help you take the next step.”
Ian has worked in financial services since 1983. He built this site so that the things advisers explain in a first meeting are written down, for free, for anyone who wants to read them.
The next step
There is no form on this site
We are not going to ask for your email address, and nothing here is trying to sell you a meeting. When you have read enough to feel confident, the next step is to open an account with a regulated investment platform and choose your own investments.
Our directory lists UK platforms authorised by the Financial Conduct Authority, alphabetically, with no ranking and no affiliate links, so you can compare them yourself.
Information, not advice. Everything on this site is general information to help you understand your options. It is not personal advice and not a recommendation to buy, sell or hold any investment. If you are unsure whether an investment is right for you, consider taking regulated financial advice. The value of investments and any income received from them can fall as well as rise, and investors may receive back less than they originally invested. Past performance is not a guide to future returns.